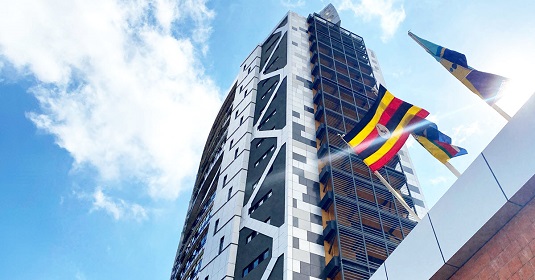
URA headquarters in Nakawa, Kampala.
Uganda’s Court of Appeal has dismissed an appeal by Goodways Trustees Limited against the Uganda Revenue Authority (URA) over unpaid taxes and the foreclosure of the company’s right to redeem land in Makerere.
The case arose from a High Court judgment that allowed URA to recover outstanding tax through land comprised in Kibuga Block 28 Plot 334. The tax authority had initially claimed UGX 502,029,354 in unpaid corporation tax, including assessments and interest dating from 1996 to 2004. URA later registered a charge over the property after repeated demands for payment went unanswered. Goodways Trustees denied owing the claimed amount, arguing that an audit of its accounts showed its liability was only UGX 4,605,245.
The company also contended that correspondence forwarding the audited accounts amounted to a valid written objection to URA’s assessment. It further argued that URA’s withdrawal of a warrant of distress ended the enforcement process and reopened the assessment for review. URA maintained that, even after the Finance Act 2008 waived income tax arrears outstanding before July 1, 2002, Goodways still owed UGX 205,127,100 for the period from August 1, 2002 to December 30, 2004.
The High Court agreed, giving the company six months to pay the amount or face the sale of the property by private treaty.
In a judgment delivered in Kampala on October 12, 2026, Deputy Chief Justice Moses Kazibwe Kawumi upheld the lower court’s decision. He rejected the company’s argument that its audited accounts constituted a valid objection, noting that the warrant of distress had been withdrawn before the audited statements were filed.
“The letter withdrawing the Warrant of Distress from M/S Kamugasha Agencies attached as evidence for the appellant is dated November 7, 2006. It is therefore not possible, based on the evidence adduced, that the withdraw of the warrant was a consequence of an objection by the appellant, following the discovery through an audit that the appellant’s tax liability was only UGX 4,505, 245l= instead of UGX 306,115,450/=. It is clear that the warrant was withdrawn on November 7, before the audited financial statements were filed on November 15. In this regard, it is apparent to me that it is Counsel for the appellant who ignored the documentary evidence and not the learned trial Judge,” the judge said.
The court also found that the audited accounts covered only one financial year and did not address the entire period for which the tax had been assessed. It held that Goodways had failed to lodge a formal objection within the period prescribed by the Income Tax Act.
“The record shows that after continuous reminders, a charge was lawfully placed on the appellant’s property as security for unpaid tax. The assertion that the charge collapsed upon the withdrawal of the warrant of distress is not plausible. The charge could only be removed upon payment of the taxes due,” Justice Kawumi observed.
The court further ruled that statutory time limits are matters of law and cannot be treated as mere technicalities. Because Goodways failed to challenge the assessment within the prescribed period, it could not reopen the matter through later correspondence or the filing of audited accounts.
“I therefore cannot fault the trial Judge for relying on this amount as the outstanding tax liability after the waiver,” the judge said, referring to the UGX 205,127,100 assessed as payable after the tax amnesty. The appellate court unanimously dismissed the appeal and ordered Goodways Trustees Limited to pay the costs of the proceedings both in the Court of Appeal and the High Court.
About The Author