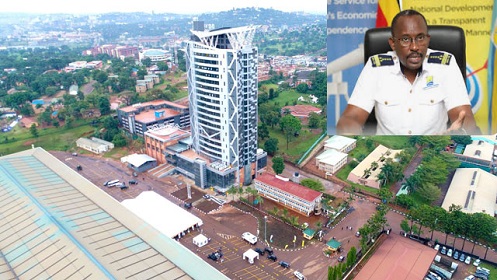
URA Tower, the home of the Uganda Revenue Authority. Inset is the CG John R. Musinguzi.
The High Court has dismissed an appeal by Cheffette Catering Ltd challenging the Tax Appeals Tribunal’s refusal to extend time for the company to contest tax assessments issued by the Uganda Revenue Authority (URA).
In a ruling delivered on October 14, 2026, Justice Susan Odongo upheld the Tribunal’s decision and ordered Cheffette to pay the costs of the appeal. The dispute arose from a URA audit covering the company’s operations between July 2016 and June 2019, including financial years 2016–2017 to 2020–2021.
URA assessed Cheffette for UGX 314,165,238 in income tax and UGX 97,959,102 in VAT over alleged undeclared sales. The company objected to the assessments and sought further administrative review through URA’s Alternative Dispute Resolution Division. URA later served its objection decision on March 21, 2024, maintaining the assessments.
Cheffette said it instructed its former lawyers, Ntambirweki Kandeebe & Co. Advocates, to file a review application before the Tribunal, but the lawyers allegedly failed to do so within the statutory 30-day period. The company discovered the omission after URA issued a third-party agency notice to Standard Chartered Bank on January 29, 2025, seeking to collect UGX 124,002,018. It then instructed new lawyers, who filed an application for extension of time on February 14, 2025. The Tribunal dismissed the application, citing the company’s 11-month delay and failure to provide sufficient evidence proving that its former lawyers had caused the default.
On appeal, Cheffette argued that the Tribunal had placed an unnecessary burden on it to monitor its lawyers and had considered the length of delay without properly examining other relevant factors. URA maintained that the delay was inordinate and that the company had not produced written instructions or evidence of diligent follow-up. Justice Odongo held that mistake of counsel may constitute reasonable cause, but an applicant must first prove that clear instructions were given, accepted and directly linked to the failure to file the case.
“Before an applicant can claim that it relied on its advocate to its detriment, the applicant bears both the legal and evidentiary burden of adducing admissible, primary, and corroborative evidence proving: (a) that clear, unambiguous legal instructions were actually conveyed to the advocate within the statutory period; (b) that the advocate accepted those instructions; and (c) that the failure to lodge the appeal was caused directly by the advocate’s genuine mistake, oversight, or default, rather than the client’s own inaction or failure to provide necessary facilitation,” the Judge said.
She added: “Thus, while the Appellant correctly asserted that a client is entitled to rely on its advocate, it failed on the evidence to establish that its former advocate was ever properly instructed or that any advocate’s mistake actually occurred.”
The court nevertheless found that the Tribunal had erred by suggesting that represented litigants must independently monitor registry filings. It held, however, that the error did not justify overturning the decision because the Tribunal reached the correct result on the evidence.
“In the result, the Tax Appeals Tribunal properly evaluated the record, correctly applied the legal parameters governing statutory discretion, and rightly held that the Appellant’s 11-month unexcused delay barred the grant of an extension of time,” Justice Odongo ruled.
The appeal was dismissed in its entirety, the Tribunal’s ruling was affirmed, and Cheffette was ordered to pay URA’s costs.
URA CG appeals to compliance
Meanwhile, the URA Commissioner General John Musinguzi has appealed for greater compliance, urging everyone to pay their fair share of taxes.
Tax non-compliance remains a concern despite growing contributions from the financial sector. While many institutions report strong profits reflected in dividends, some still fall short of meeting their full tax obligations, undermining fairness in the tax system.
Delayed payments, unresolved disputes, and incomplete disclosures continue to pose challenges, with some cases dragging on for years.
These gaps highlight the need for stronger collaboration, enforcement, and better cooperation between taxpayers and authorities. The CG emphasized that institutions have a responsibility not only to clients but to the country, urging them to pay their fair share and actively support the tax compliance processes.
Overall, he called for greater accountability, timely compliance, and a shared commitment to national development through proper tax practices.
About The Author


